With mortgage rates significantly higher than they were just a few years ago, buyers are looking for creative ways to make homeownership more affordable. One option gaining renewed attention is the assumable mortgage, a financing tool that can potentially save buyers hundreds or even thousands of dollars each month.
I have helped clients navigate this process multiple times. While an assumption can be more challenging than a traditional transaction, the potential savings can make it well worth the effort.
WHAT IS AN ASSUMABLE MORTGAGE?
An assumable mortgage allows a qualified buyer to take over the seller’s existing home loan, including its interest rate, remaining balance and repayment terms.
For example, if a homeowner secured a mortgage at 2.75%, a qualified buyer may be able to assume that loan instead of financing the purchase entirely at today’s higher rates.
The most common assumable loans are FHA, VA and USDA loans. Most conventional mortgages are not assumable, so eligibility should always be verified with the loan servicer.
WHY IT MATTERS
The biggest advantage is the lower interest rate. A difference of just a few percentage points can significantly reduce monthly payments and create substantial long-term savings.
For sellers, an assumable low-interest mortgage can also be a powerful marketing advantage, helping a property stand out in a competitive market.
There is a catch: buyers typically must cover the difference between the purchase price and the remaining loan balance, known as the equity gap. This may require cash or secondary financing.
When considering how to bridge that difference, buyers should consult an experienced lender about their individual situation. Katie Simmons Hickey of the Simmons Group at CrossCountry Mortgage is an excellent local resource and can be reached at 703-300-1590 or katie.hickey@ccm.com.
TWO LOCAL OPPORTUNITIES
I currently represent two properties offering buyers access to historically low assumable mortgage rates.
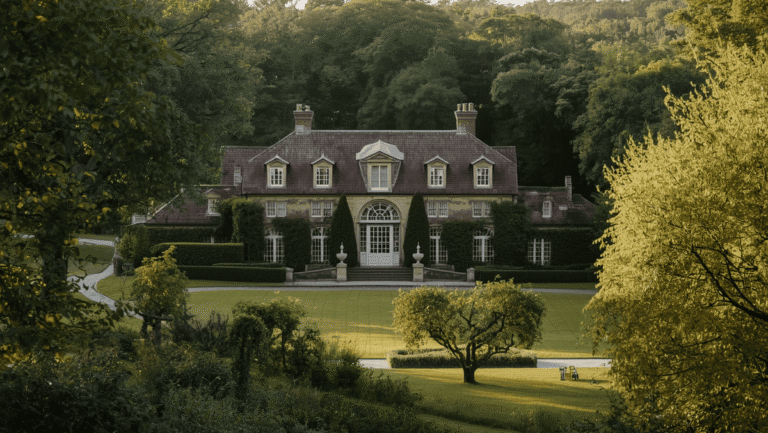
Great Falls: Near Riverbend Country Club, Fleur House is a custom French Provincial home listed at $2 million, with an assumable VA loan balance of approximately $800,000 at 2.75%. Because the owners do not intend to retain their VA entitlement, the assumption is available to any qualified buyer.
For comparison, principal and interest on $800,000 at 2.75% would be approximately $3,266 per month, compared with approximately $5,058 at 6.5%—a difference of roughly $1,800 per month.
Reston Town Center: A two-bedroom residence at Midtown North is listed at $790,000 with an assumable VA loan balance of approximately $460,000 at 2.25%. Because the seller intends to retain the VA benefit, this opportunity is available to qualified veterans.
On that $460,000 balance, estimated principal and interest at 2.25% would be approximately $1,758 per month, compared with approximately $2,908 at 6.5%—a savings of roughly $1,150 per month.
IS AN ASSUMABLE MORTGAGE RIGHT FOR YOU?
Assumable mortgages are not right for everyone. Buyers must qualify, the loan servicer must approve the assumption, and the equity gap may require additional financing.
But when the numbers work, the savings can be significant. For buyers, an assumable mortgage can provide access to an interest rate that may no longer be available in today’s market. For sellers, it can become a compelling feature that differentiates a property. In the right situation, an assumable mortgage may be one of the most valuable—and overlooked—tools in today’s real estate market.
If you are curious whether a home qualifies for a loan assumption or how an assumable mortgage could affect your buying or selling strategy, I am happy to walk you through the options.
Any content, resident submissions, guest columns, advertisements, and advertorials are not necessarily endorsed by or represent the views of Best Version Media LLC (BVM) or any municipality, homeowners associations, businesses, or organizations that this publication serves. BVM is not responsible for the reliability, suitability, or timeliness of any content submitted, inclusive of materials generated or composed through artificial intelligence (AI). All content submitted is done so at the sole discretion of the submitting party.