If you’ve lived in North Louisiana for any length of time, you know our weather can be unpredictable. One day may bring sunshine and blue skies, while the next delivers hail, damaging winds, or even tornadoes. Yet despite the storms that regularly impact our region, many homeowners hesitate to use one of the protections they’ve already paid for—their homeowners insurance policy.
As a roofing contractor, I’ve met countless homeowners standing in their yard after a storm, looking at visible roof damage and saying the same thing: “I don’t want to file a claim because they’ll raise my rates or drop my coverage.”
Unfortunately, that fear often leads people to make costly decisions.
Some homeowners pay for repairs out of pocket when they may have legitimate storm damage covered by their policy. Others delay repairs altogether, hoping the problem will go away. In many cases, a relatively minor roofing issue eventually becomes a much larger and more expensive problem involving water intrusion, damaged insulation, stained ceilings, and structural deterioration.
What many people don’t realize is that Louisiana law has provided important protections for homeowners for nearly two decades.
Following Hurricanes Katrina and Rita, lawmakers addressed concerns surrounding storm-related insurance claims. In 2007, Senate Bill 204 was passed as part of broader insurance reform efforts. The law prevents insurers from using certain storm-related losses—often referred to as “Acts of God”—as grounds for canceling or refusing to renew a homeowner’s policy.
For homeowners, this is an important distinction. Damage caused by hail, tornadoes, straight-line winds, and other natural weather events falls into a different category than many people assume. Yet the misconception that filing a legitimate storm claim automatically results in higher rates or policy cancellation continues to circulate throughout communities across Louisiana.
Another source of confusion comes from homeowners comparing roofing claims to automobile insurance claims.
While both involve insurance coverage, the laws governing homeowners and auto policies are different. In fact, Louisiana lawmakers later passed separate legislation addressing similar concerns for automobile coverage. Understanding that distinction can help homeowners make more informed decisions when evaluating storm damage to their property.
One fact that surprises many people is that a new roof is often one of the least risky assets for an insurance company to insure. A properly installed roof built to modern standards helps reduce the likelihood of future water damage and costly claims. In many cases, newer roofing systems provide better protection than the materials they replace.
Homeowners may also benefit from newer roofing technologies. Class 4 impact-resistant shingles, for example, often qualify for insurance discounts with many carriers. Depending on the company and policy, those savings can be significant. Louisiana’s Fortify Homes Program has also increased awareness about stronger, more resilient roofing systems designed to better withstand severe weather.
While understanding your insurance rights is important, timing is equally critical.
One of the most common mistakes homeowners make is waiting too long to address storm damage. Every insurance policy contains its own requirements and deadlines, and some policies change how claims are handled after a certain amount of time has passed.
The longer damage sits unaddressed, the more difficult it can become to determine exactly when it occurred. After major storms, it’s not uncommon for homeowners, adjusters, and contractors to find themselves debating whether damage came from a recent weather event or one that happened months—or even years—earlier.
That’s why documentation matters.
North Louisiana has experienced some of its most severe weather during the late fall and early winter months in recent years, making this an ideal time for homeowners to assess the condition of their roof before storm season intensifies.
Fortunately, there are several things homeowners can safely do themselves.
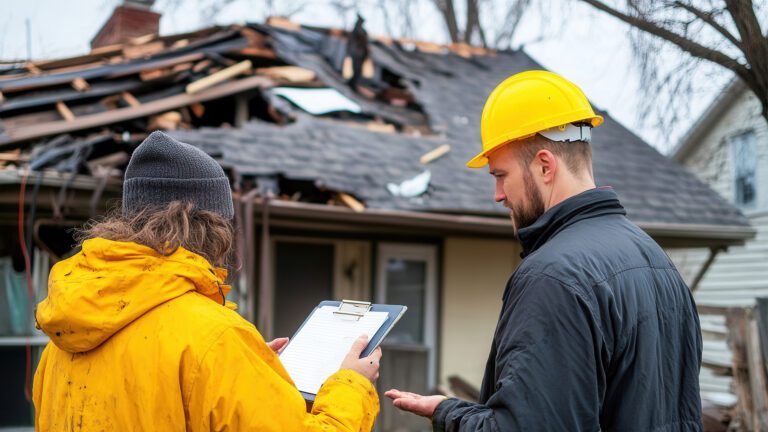
Start by staying on the ground. Walk around your home and look for loose granules collecting near downspouts or scattered across driveways and walkways. Visually inspect the roofline for shingles that appear lifted, missing, or out of place. Inside the home, check the attic for signs of water staining on the roof decking while remaining in safe, walkable areas.
However, it’s important to understand the limits of a visual inspection.
Many forms of hail damage are difficult for an untrained eye to identify. What appears to be normal wear may actually be storm-related damage, while some issues homeowners assume are roof leaks may originate from other sources entirely.
That’s why a professional inspection is often the most valuable first step.
Before contacting your insurance carrier, understand your deductible and obtain a documented inspection from a qualified professional. A thorough inspection should include photographs and written documentation that can be referenced later if questions arise regarding the condition of the roof.
Homeowners should also be cautious when approached by individuals offering immediate roofing services following a storm. Taking time to verify credentials, review documentation, and avoid signing agreements on the spot can help prevent unnecessary complications later.
At the end of the day, your homeowners insurance policy is a contract you’ve paid for. Understanding your coverage, knowing your rights, and addressing storm damage promptly can help protect one of your family’s largest investments.
Don’t let outdated misconceptions prevent you from making informed decisions about your home. Whether damage is found or not, having a professional assessment and proper documentation can provide peace of mind and help ensure you’re prepared for whatever Louisiana weather brings next.
Daniel Gilley is the owner of Gilley Roofing and has worked with homeowners throughout North Louisiana for years. For more information, contact Gilley Roofing at 318-878-7663 or visit gilleyroofing.com. This article reflects professional experience and general industry knowledge and should not be considered legal advice. Homeowners should consult their insurance provider regarding specific policy questions.
Any content, resident submissions, guest columns, advertisements, and advertorials are not necessarily endorsed by or represent the views of Best Version Media LLC (BVM) or any municipality, homeowners associations, businesses, or organizations that this publication serves. BVM is not responsible for the reliability, suitability, or timeliness of any content submitted, inclusive of materials generated or composed through artificial intelligence (AI). All content submitted is done so at the sole discretion of the submitting party.