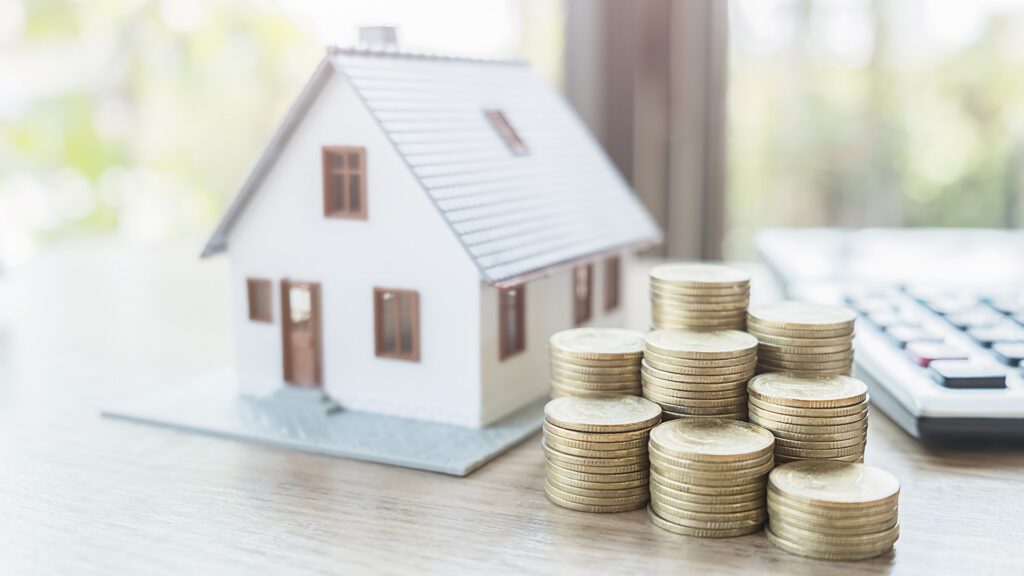
If your home could sell for $450,000 today, how much do you think you should insure it for? $450,000 seems like the obvious answer.
But when it comes to homeowners’ insurance, what your home is worth and what it would cost to rebuild it are two very different numbers. Especially in Alaska, the difference can be significant.
Market Value Vs Replacement Cost
Market value is what someone may be willing to pay for your property. It includes things insurance isn’t trying to replace, such as your land. Market value can be influenced by:
- Location and neighborhood
- Acreage
- School Districts
- Housing supply and demand
- Interest rates
- Views and waterfront access
- The local real estate market
Replacement cost, on the other hand, asks a completely different question: If your home were destroyed today, approximately what would it cost to rebuild it with materials of similar kind and quality?
Your homeowner’s insurance isn’t buying your property from you. It’s designed, subject to your policy’s terms and limits, to help repair or rebuild the insured structure after a covered loss. That’s why simply looking at your home’s purchase price, tax assessment, appraisal or an online real estate estimate doesn’t tell you how much dwelling coverage you need.
A $450,000 Home Could Cost $600,000 to Rebuild
Imagine you purchased your home for $450,000. Then imagine a fire causes a total loss. You already own the land. You don’t need to purchase another piece of property. What you may need is contractors, lumber, roofing, drywall, electrical work, plumbing, flooring, cabinetry, appliances, permits, debris removal and dozens of other pieces required to reconstruct a home.
Suddenly, the question isn’t: “What could sell my house for?” It’s: “What would it cost to build this house again?”
Those numbers aren’t always the same. In fact, sometimes replacement cos can be higher than market value. Other times, particularly when land represents a significant portion of a property’s value, market value can be higher than the estimated cost to rebuild the structure. Neither number is necessarily wrong, they’re simply measuring two different things.
Alaska Adds Another Layer
Building in Alaska comes with some unique realities. Materials may have to travel farther; certain contractors and skilled trades can be in high demand. Labor costs change, transportation costs change, building requirements change. The price of construction materials certainly doesn’t stay the same forever.
There’s also an important difference between building a home under ideal circumstances and rebuilding one after a loss. After a major fire or other covered loss, you’re not starting with a clean, empty lot and a perfectly planned construction schedule. There may be damaged materials to remove, demolition work to complete, permits to obtain and an existing structure that has to be reconstructed.
After a widespread disaster, another issue can arise. A lot of people may need contractors and materials at the same time. Supply goes down, demand goes up, then rebuilding costs can follow.
Your Home Changes, Too
There’s another reason it’s worth reviewing your replacement cost periodically. The house you’re living in today may not be the same house you originally insured. Maybe you’ve finished the basement, remodeled the kitchen, added a bathroom, built an addition, upgraded flooring. Those improvements may increase the cost to reconstruct your home, but your insurance company can’t account for changes they don’t know about.
So, How Much Should Your Home Be Insured For?
There’s no universal dollar amount or simple price-per-square-foot calculation that works for every house. Insurance companies use replacement cost estimating tools that consider characteristics such as square footage, construction type, number of stories, bathrooms, flooring, roofing, interior finishes, garages, basements and other features.
But those estimates are only as good as the information being used. That’s where you come in. When reviewing your homeowner’s insurance, don’t just ask “How much is my house insured for?” Ask: “What information are we using to estimate what it would cost to rebuild my house?”
The Bottom Line
Your home’s market value matters when you’re buying it, selling it or evaluating your finances. Your home’s replacement cost matters for an entirely different reason. It’s about answering one very important question: If something happened to my home tomorrow, what could it take to put it back?
For Alaska homeowners especially, that’s a conversation worth having before you ever need the answer.
Any content, resident submissions, guest columns, advertisements, and advertorials are not necessarily endorsed by or represent the views of Best Version Media LLC (BVM) or any municipality, homeowners associations, businesses, or organizations that this publication serves. BVM is not responsible for the reliability, suitability, or timeliness of any content submitted, inclusive of materials generated or composed through artificial intelligence (AI). All content submitted is done so at the sole discretion of the submitting party.