Estate planning is often thought of as something that takes effect after you’re gone, but it can also play an important role in preparing for potential healthcare needs during your lifetime. If you become unable to make decisions for yourself or require long-term care, a thoughtful plan can help ensure your wishes are honored while helping preserve your financial stability and support the people who matter most to you. A financial advisor can work alongside your estate planning team to help align financial and healthcare considerations. The following steps can help guide the process.
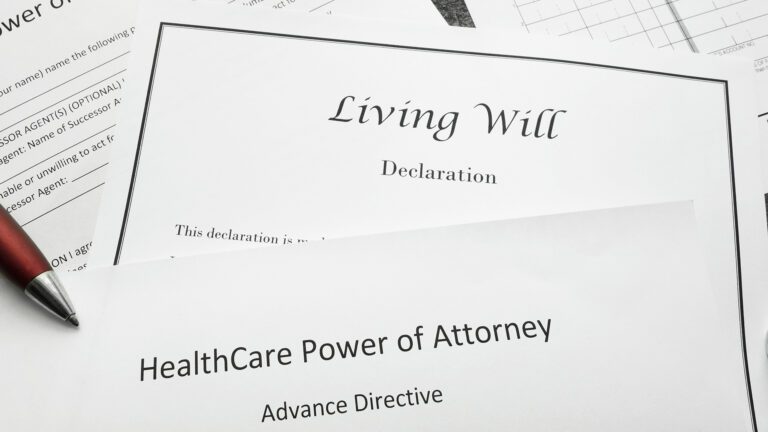
Document your healthcare wishes. An advance healthcare directive, sometimes called a living will, outlines your preferences for medical treatment if you are unable to communicate them yourself. It can clarify the types of care you do or do not want in certain situations, helping reduce uncertainty for loved ones during difficult moments. Because requirements vary by state, it is important to work with an attorney to ensure your document is valid and complete, including a HIPAA authorization. Keeping copies accessible and sharing them with key people in your life can help ensure your wishes are followed when they matter most.
Appoint trusted decision-makers. Naming a healthcare proxy and a durable power of attorney are essential steps in preparing for the unexpected. A healthcare proxy authorizes someone you trust to make medical decisions on your behalf if needed, while a durable power of attorney allows a designated individual to manage financial matters during periods of incapacity. These roles carry significant responsibility, so it is important to choose individuals who understand your values, can navigate complex decisions, and are willing to act in your best interest. Naming alternates can provide additional continuity if circumstances change.
Plan for potential long-term care needs. As life expectancy increases, so does the likelihood of needing extended care later in life. Whether care is provided at home or in a facility, costs can be substantial. Evaluating how these expenses might be covered, through personal savings, family support, or insurance solutions, can help reduce financial strain. Options such as long-term care insurance or life insurance with care-related benefits may help manage risk while preserving assets intended for future goals or legacy planning.
Prepare thoughtfully for what lies ahead. Addressing healthcare concerns is not about expecting the worst, but about creating clarity, dignity, and support in uncertain moments. With a well-structured plan in place, it becomes easier to navigate health-related challenges with greater confidence, knowing that both your wishes and your financial well-being have been considered. A financial advisor can help bring these elements together into a coordinated plan that supports you and your loved ones over time.
Ameriprise Financial, Inc. and its affiliates do not offer tax or legal advice. Consumers should consult with their tax advisor or attorney regarding their specific situation.
Ameriprise Financial cannot guarantee future financial results.
Investment products are not insured by the FDIC, NCUA or any federal agency, are not deposits or obligations of, or guaranteed by any financial institution, and involve investment risks including possible loss of principal and fluctuation in value.
Securities offered by Ameriprise Financial Services, LLC. Member FINRA and SIPC.
© 2026 Ameriprise Financial, Inc. All rights reserved.
Any content, resident submissions, guest columns, advertisements, and advertorials are not necessarily endorsed by or represent the views of Best Version Media LLC (BVM) or any municipality, homeowners associations, businesses, or organizations that this publication serves. BVM is not responsible for the reliability, suitability, or timeliness of any content submitted, inclusive of materials generated or composed through artificial intelligence (AI). All content submitted is done so at the sole discretion of the submitting party.