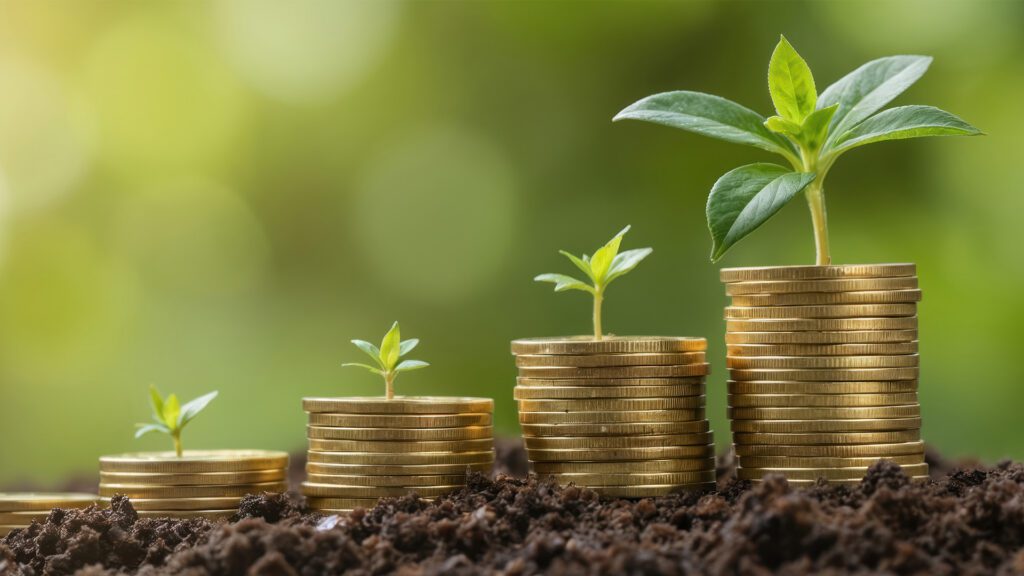
Making a budget rarely tops anyone’s to-do list. But a budget isn’t a restriction. It’s one of the most practical steps you can take for your financial future. Pay yourself first! There are four main uses for money, spending, saving, investing, and giving. Finding the right balance among them is the goal, and a budget is the tool that helps you get there. The guiding principle is simple, pay yourself first. Before bills and discretionary spending, set something aside for your future.
Get Going
Start by recording your short- and long-term financial goals. A new phone, a vacation, a car, a house, continued education, etc. That list becomes your baseline, the reason behind every dollar you set aside.
Here’s a great budgeting formula to consider. Many people budget backwards, they total their expenses and save whatever remains. A more effective approach flips the order. Income minus savings equals expenses. Decide your savings first, then cover expenses from what’s left. When saving is prioritized up front, the more likely you are to stick with it.
Five Benefits of a Detailed Budget
A detailed budget pays off in several ways. It tracks cash in versus cash out, giving you a clear picture of where your money goes and how much to set aside for short- and long-term goals. It keeps monthly bills and expenses manageable, turning unpredictable due dates into a routine. It prepares you for the unexpected, so a car repair stays an inconvenience rather than a crisis. And it reduces the likelihood of overspending, since a plan provides a built-in check on impulse spending.
Structure Your Savings
Make saving automatic and set aside a regular amount each pay period. A pre-authorized contribution plan that auto-deposits into a savings or investment account works well. Consistency matters more than the amount, and automating the process removes the need for willpower.
What a Good Budget Tracks
A solid budget accounts for four things, your income, your savings goals, your fixed expenses such as rent, utilities, and insurance, and your flexible expenses. Flexible expenses are best split into what’s needed—like groceries and gas—and what’s wanted, like dining out or streaming subscriptions.
You don’t need specialized software to begin. A notebook and a pen are enough to start. What matters is building the habit. Record your goals, pay yourself first, automate what you can, and let the structure do the rest.
Any content, resident submissions, guest columns, advertisements, and advertorials are not necessarily endorsed by or represent the views of Best Version Media LLC (BVM) or any municipality, homeowners associations, businesses, or organizations that this publication serves. BVM is not responsible for the reliability, suitability, or timeliness of any content submitted, inclusive of materials generated or composed through artificial intelligence (AI). All content submitted is done so at the sole discretion of the submitting party.