A Mortgage Broker’s Perspective for Today’s Homebuyers
One of the biggest myths I hear from potential homebuyers is, “I’ll call you when I’ve saved 20% down.” While having a 20% down payment can be beneficial, the reality is that many buyers become homeowners with far less.
As a mortgage broker, I regularly help clients discover loan programs that allow them to buy a home sooner than they thought possible.
Where Did the 20% Rule Come From?
The 20% down payment guideline became popular because it helps borrowers avoid Private Mortgage Insurance (PMI) on conventional loans. PMI protects the lender if the borrower defaults, and it adds an additional monthly cost to the mortgage payment.
However, avoiding PMI and qualifying for a mortgage are two very different things. Many loan programs require significantly less money upfront.
Submitted photo
Low Down Payment Options Available
- Conventional Loans: as little as 3% down for eligible first-time
- FHA Loans: typically 3.5% down with qualifying
- VA Loans: up to 100% financing for eligible veterans and active-duty military
- USDA Loans: up to 100% financing in qualified rural
- State and Local Assistance Programs: grants and down payment assistance may be
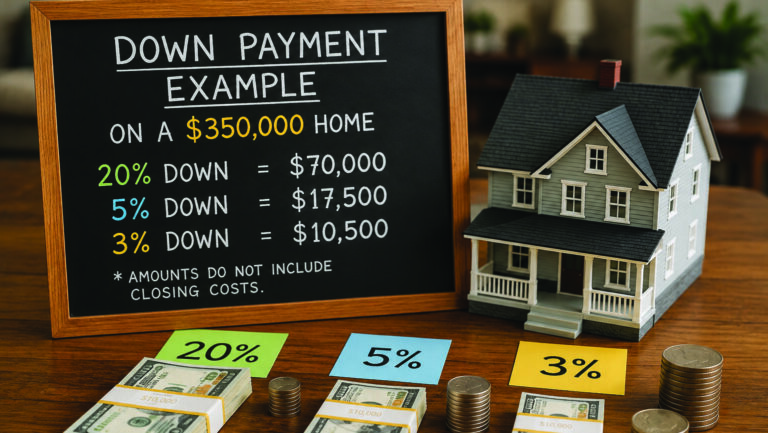
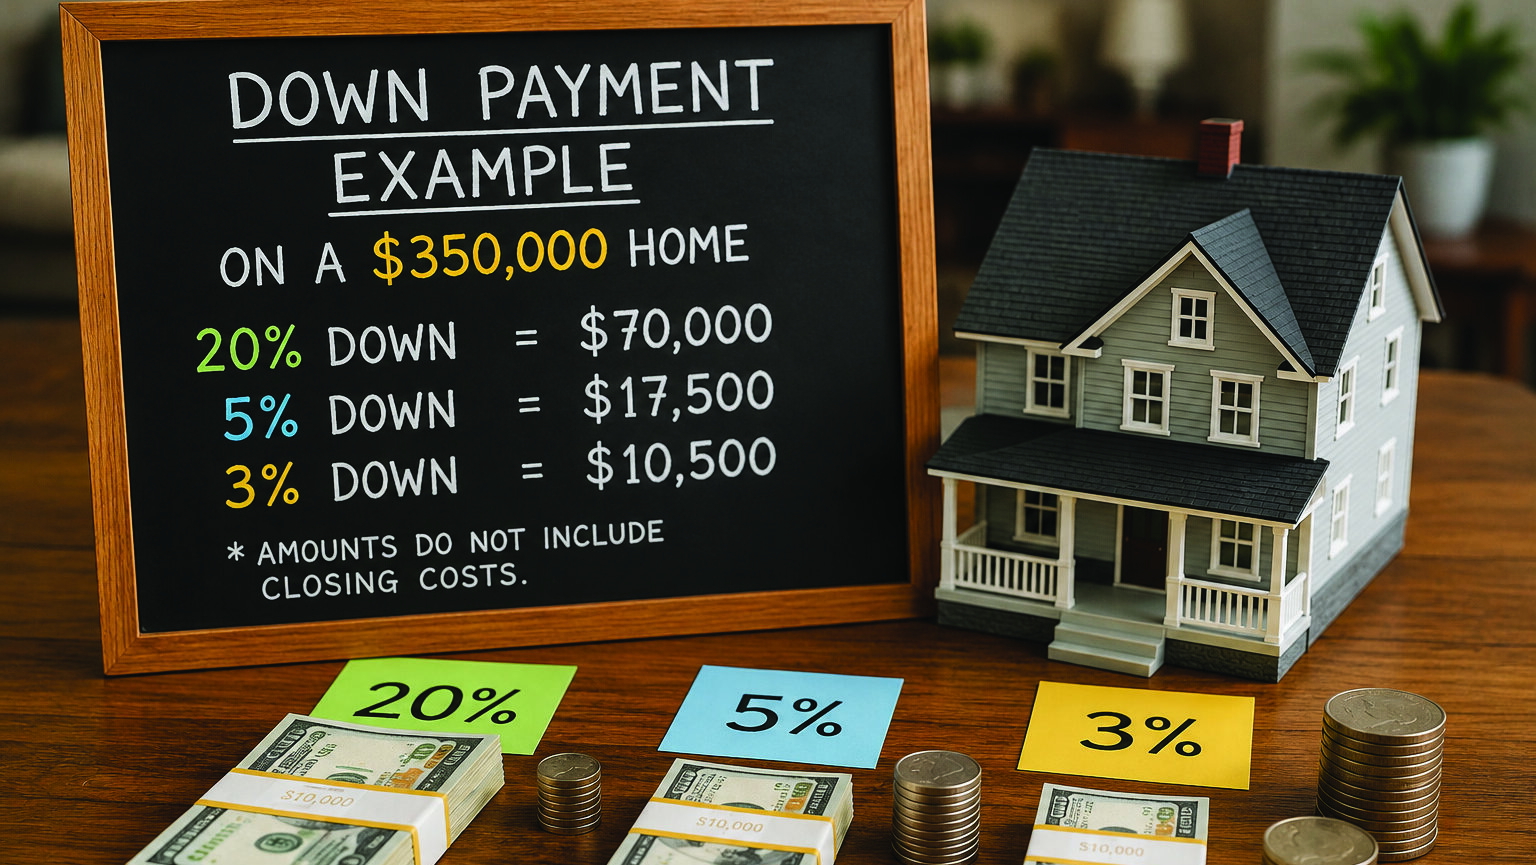
For example, on a $350,000 home: 20% down = $70,000; 5% down = $17,500; 3% down = $10,500.
When 20% Down Makes Sense
There are certainly advantages to putting 20% down: lower monthly payments, no PMI on most conventional loans, greater initial equity, and potentially stronger offers in competitive markets.
The Bigger Question: Is It the Right Time?
Instead of focusing solely on the size of your down payment, consider your income stability, debt levels, credit profile, savings for closing costs, and emergency reserves.
Final Thoughts
The biggest mistake many aspiring buyers make is assuming they need 20% down before speaking with a mortgage professional. Today’s mortgage market offers more flexibility than many people realize. Don’t count yourself out before exploring your options. A quick mortgage consultation may reveal that homeownership is much closer than you think.
At Everest Lending LLC, my role as a mortgage broker is not just to secure financing, but to help clients make strategic decisions that strengthen their financial future.
James DiBattista is a Mortgage Broker at Everest Lending LLC, where for 26+ years he has helped homebuyers and homeowners navigate the mortgage process with clarity, confidence, and personalized guidance.
Any content, resident submissions, guest columns, advertisements, and advertorials are not necessarily endorsed by or represent the views of Best Version Media LLC (BVM) or any municipality, homeowners associations, businesses, or organizations that this publication serves. BVM is not responsible for the reliability, suitability, or timeliness of any content submitted, inclusive of materials generated or composed through artificial intelligence (AI). All content submitted is done so at the sole discretion of the submitting party.