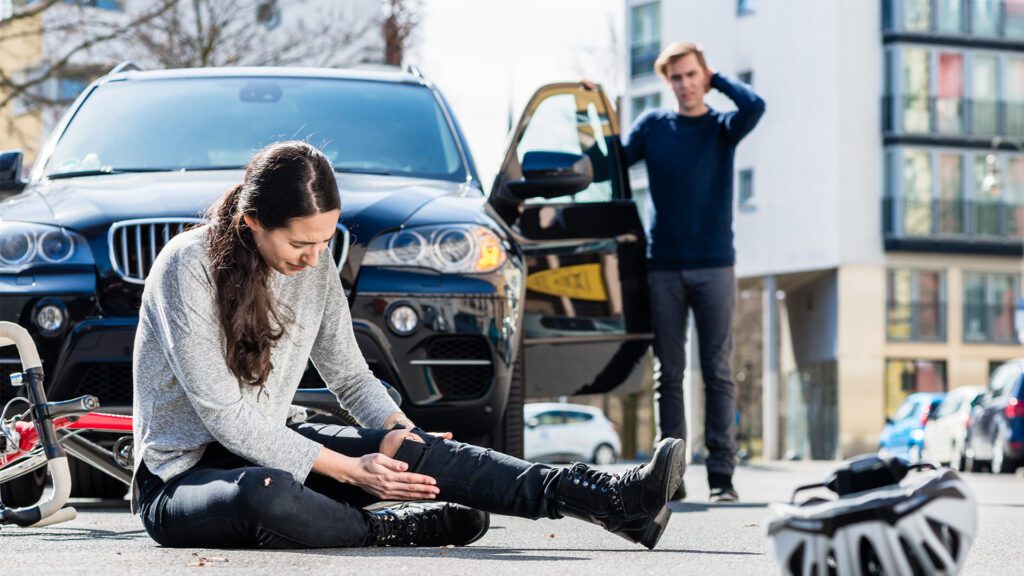
MedPay, short for Medical Payments Coverage, is an optional add-on to your automobile insurance policy. In Mississippi, it is not required, but adding MedPay with a $5,000 limit may cost around $5 to $8 per month. MedPay helps cover medical expenses if you or your passengers are injured in a car accident, regardless of who caused the crash. But it has a downside.
So, do you need it? The answer depends on your health insurance, your deductible, your financial situation, and how much risk you are comfortable with.
What Does MedPay Cover?
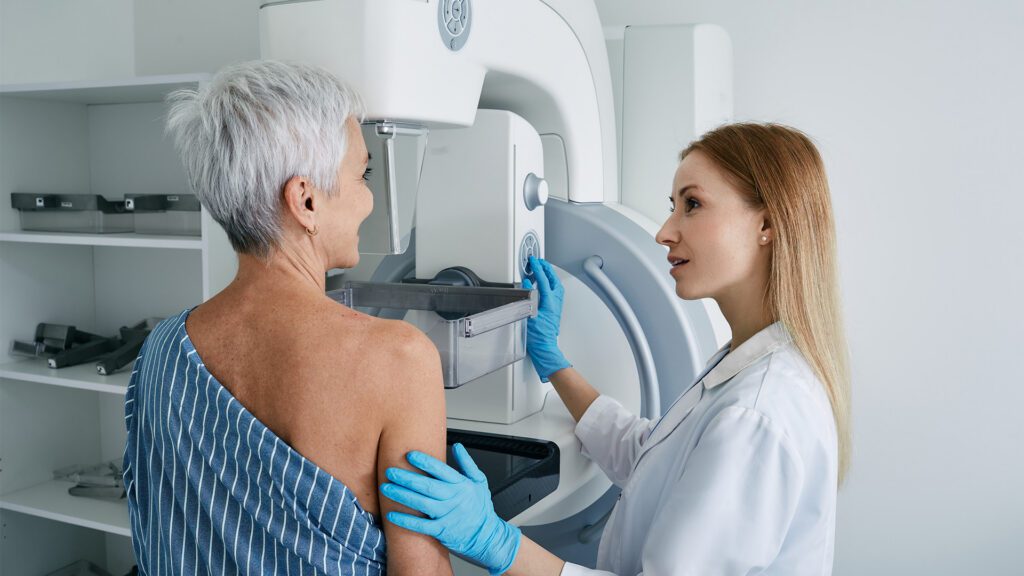
MedPay covers accident-related medical expenses incurred after a car or truck wreck, including hospital bills, doctor visits, ambulance fees, imaging, physical therapy, and surgery-related expenses.
One of the biggest benefits of MedPay is speed. It can help pay medical bills before the at-fault driver’s insurance company accepts responsibility or before a personal injury settlement is reached. That can be important because medical bills often arrive long before an injury claim is resolved.
Why Do Medical Providers Like MedPay?
Hospitals and medical providers prefer MedPay because it often pays them more than health insurance, which typically pays discounted rates under provider contracts.
This financial incentive leads some providers—especially hospitals, emergency room contractors, and ambulance services—to manipulate the order in which insurers are billed after an auto accident, using MedPay before health insurance. This can quickly exhaust MedPay at higher rates, leaving less available for other treatment and losses. It can also create a billing nightmare when your provider, health insurer, MedPay carrier—and even you—are left trying to sort out who should have paid what.
And believe me, unraveling a MedPay mess can feel like a sinister game of “Who’s on First?” that is designed to keep you from figuring out who is supposed to pay what to whom.
Could You Owe Your Insurance Company?
Actually, yes. A car wreck victim can often end up owing their own insurance company money after a car wreck. If your MedPay carrier pays your medical bills and you later recover a settlement, your auto insurer may demand reimbursement for what it paid. This is called subrogation, and it’s a bear!
Before using MedPay, understand this: handling it wrong can cost you thousands of dollars. Many people assume that if their own insurance pays medical bills, they will automatically keep more money. With the right strategy, they may—but not always.
When MedPay Might Not Be Necessary
MedPay may not be necessary if you have good health insurance, low deductibles, low co-pays, and a manageable out-of-pocket maximum. If your health insurance will promptly cover accident-related treatment, MedPay may be redundant.
Used Strategically, MedPay Can Be Useful!
MedPay can be used to help speed up a case, and save you money, especially with a lawyer’s strategic guidance. It can also help if you have high health insurance deductibles, co-pays, or no health insurance at all.
When Could You Skip It?
If you already have a strong health insurance plan, MedPay may not add much benefit. You are already paying your health insurer to cover medical bills, and injuries from a car accident are usually covered by health insurance.
Additionally, MedPay can create a bureaucratic shell game that benefits the health insurer instead of the policy holder. Often, MedPay actually protects the health insurer’s bottom line instead of yours. Once a wreck is involved, some health insurers refuse to pay accident-related bills until MedPay is exhausted, if their contract permits it.
Instead of a single insurer just honoring the coverage you bought, you are waiting on two companies to “do what’s right” while each points at the other, or their contract. Meanwhile, medical providers can exhaust MedPay at rates far higher than health insurance would have paid. You get delays, collection notices, and less money for other harms and losses; the health insurer gets to sit on the sidelines.
I once asked a lobbyist in Jackson whether “the powers that be” would ever allow the Mississippi Legislature to require health insurers to pay car-wreck-related claims before MedPay is exhausted. The lobbyist just laughed at the idea.
Bottom Line
You may not need MedPay if you have solid health insurance, low out-of-pocket costs, and enough savings to handle smaller medical bills after a crash. But if your health insurance is weak, your deductible is high, or you want an extra layer of protection, MedPay can make sense.
The key is understanding how it works. MedPay can help pay bills quickly, but it may also have to be reimbursed later. Used carefully, it can be a helpful safety net. Used without a plan, it can create billing problems, reduce the money you take home from a settlement, or actually cost you money.
Any content, resident submissions, guest columns, advertisements, and advertorials are not necessarily endorsed by or represent the views of Best Version Media LLC (BVM) or any municipality, homeowners associations, businesses, or organizations that this publication serves. BVM is not responsible for the reliability, suitability, or timeliness of any content submitted, inclusive of materials generated or composed through artificial intelligence (AI). All content submitted is done so at the sole discretion of the submitting party.